

Sumio: Net Worth Tracker
Fiduciary
- 3.8
- 5.00 Reviews
- 10.00K
- Downloads
- Free
- Price
Screenshots
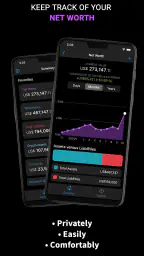
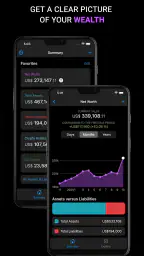
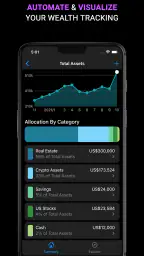
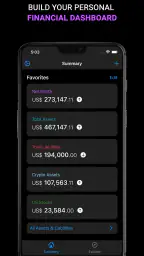
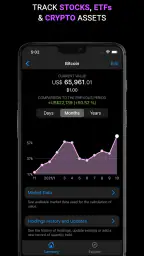
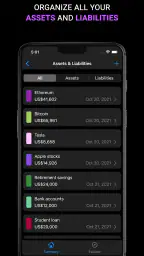
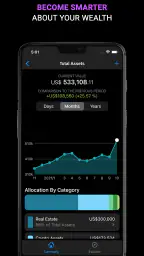
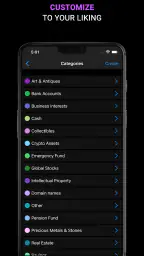
Sumio: Net Worth Tracker Pros and Cons
Pros
- Tracks assets, debts, and net worth in one organized dashboard.
- Supports recurring transactions for easier long-term financial monitoring.
- Custom categories help tailor the tracker to your personal finances.
- Charts make changes in your wealth easier to understand over time.
- Useful for setting savings goals and reviewing financial progress regularly.
Cons
- Manual data entry can become time-consuming without automatic bank syncing.
- Advanced features may require a paid subscription.
- Currency support and exchange handling may vary by region.
- Entering investment values manually can reduce portfolio accuracy.
- Some users may find detailed financial setup overwhelming at first.
 Analysis by All-app
I look at a finance app differently from a casual utility. When an app is used to record investments, assets, and personal wealth, the useful features matter, but so do the moments when I decide what to enter, what to update, and what to keep private. Sumio: Net Worth Tracker is built around that practical side of money management. It lets me bring together a personal view of net worth, an investment portfolio, stocks, funds, and other assets rather than checking each area in isolation.
After spending time with it, my impression is that Sumio is most appealing as a focused tracking tool. It does not try to replace a bank, broker, tax professional, or full budgeting system. Instead, I see it as a place to maintain a clearer snapshot of what I own and how that picture changes. That distinction is important: the app can help me understand my financial position, but it still depends on the quality and freshness of the information I record.
What Sumio is really useful for
The central idea is simple but valuable. Net worth is more meaningful when cash, investments, funds, property, and other assets are considered together. Many people know roughly how much is in a current account or brokerage account, yet have no convenient way to see the larger picture. A dedicated tracker gives those separate pieces a common home.
I found the app better suited to reflection and regular review than to rapid daily spending decisions. If I want to know whether my overall position is improving, whether investments are becoming too dominant, or whether an asset has been forgotten in my personal calculations, this kind of overview is useful. If I want detailed category budgeting, bill reminders, or transaction-by-transaction expense analysis, I would look toward a conventional budgeting app instead.
That makes Sumio a finance app with a fairly specific job. The developer is Fiduciary, and the product is free to start, with optional in-app purchases ranging from a few dollars to amounts approaching thirty dollars per item. I would therefore treat the free experience as a chance to decide whether its tracking approach fits my habits before paying for anything.
A realistic monthly routine
Imagine I receive a monthly statement from an investment provider, review my savings, and notice that the value of a fund has changed. Rather than relying on memory, I can use Sumio to update the relevant holding and then look at the wider net-worth picture. The useful part is not the single update; it is seeing whether that change matters when compared with everything else I own.
I would do this after statements arrive, not several times a day. A tracker that relies on manual attention becomes frustrating when treated like a live trading terminal. Used as a monthly or quarterly checkpoint, it encourages a calmer question: am I making progress toward my own goals, or am I reacting to one noisy market movement?
More Reads From Our News Desk

Switching to the Xbox App: What Changes in Your Gaming Routine

Coloring & Learn Review: A Satisfying Canvas, Cluttered Menus

Microsoft 365 Copilot on Your Phone: Who Actually Needs It?

Mafia City: The Crime Saga That Outshines Its Rivals

Woodturning Transformed: How OS Updates Enhance Your Craft

How Tiles Hop EDM Rush Redefines Music Gaming
One practical tip is to establish a consistent valuation date. If I update cash on one day, investments on another, and less liquid assets much later, the total can look more precise than it really is. Keeping a regular schedule makes comparisons more honest. Sumio can organize the numbers, but I still need to decide when those numbers represent a fair snapshot.
Where the overview helps—and where it can mislead
The strongest benefit is consolidation. A portfolio screen alone can make an investor feel wealthier or poorer than they are because it ignores debts, cash reserves, and non-investment assets. A net-worth view encourages a broader perspective. It can also expose concentration: an apparently diversified investment account may still represent only one part of the household’s financial position.
The trade-off is that a total figure can create false confidence. Assets do not all have the same liquidity, risk, or reliability of valuation. Cash is immediately understandable; a fund value may move daily; an item of property or another personal asset may be harder to price consistently. I would use the total as a planning reference, not as money that is instantly available.
This is one of the less obvious decisions a user has to make: whether to include an asset at all. Adding everything can create a comprehensive picture, but it can also add uncertain estimates that distract from liquid finances. For my own use, I would separate dependable values from rough estimates in my notes and compare them cautiously rather than treating every entry as equally solid.
Trust begins with what I choose to enter
Finance apps deserve a more careful review than ordinary note-taking tools because the information involved can reveal a great deal about a person. With Sumio, I would pay attention to every screen that asks me to create, edit, connect, or purchase something. The important question is not only whether the app can display a total, but whether I understand what I am giving it and why.
I would begin with a small, non-sensitive test. Entering a limited set of assets lets me learn the workflow without immediately building a complete financial profile. It also shows whether the categories, editing steps, and portfolio views make sense to me. If the process feels confusing with a small sample, adding every account will not improve the experience.
My rule for a finance tracker is simple: I should always know which number I am changing and what that change affects. A manual correction can alter the apparent total without changing the underlying money. That is not necessarily a flaw, but it means I need to distinguish between a real financial event and an updated estimate.
Controls and account decisions I would check first
Before making Sumio part of my routine, I would inspect the available account controls, sign-in choices, editing options, and any settings related to stored information. I would also review the app’s visible privacy and data disclosures before entering detailed holdings. Those checks are not a sign of distrust toward Fiduciary; they are sensible habits whenever an app handles personal financial context.
I would avoid entering information that the tracker does not need for the task I want to perform. A net-worth overview usually becomes more useful through organized values and labels, not through unnecessary personal detail. If an entry can be represented by a broad description instead of an account identifier, I would choose the broader description.
The same caution applies to optional purchases. Since the app is free but offers paid items, I would read each purchase screen carefully and confirm whether a payment unlocks a feature I will actually use. The presence of in-app purchases does not by itself tell me whether they are worthwhile. My decision would depend on how often I update my portfolio and whether the extra tools save enough effort to justify the cost.
A useful workflow is to keep a separate record of the date and source of each major update. That record does not need to contain sensitive credentials. It simply helps me remember whether a figure came from a recent statement, a market value, or my own estimate. This makes later reviews more reliable and prevents me from confusing an old number with a current one.
Handling sensitive financial moments
The most sensitive moment is not necessarily the first launch. It is often the point when I am tempted to enter everything at once: investment names, balances, property values, and other details that together reveal my financial situation. I would slow down at that stage. The app’s convenience should not push me into sharing more than I am comfortable managing.
I would also be careful when reviewing the app in public or on a shared device. A net-worth screen can expose more than a single account balance. Before showing the app to someone else, I would close the relevant view and check whether previews or recent screens could reveal financial information. These are ordinary device habits, but they matter more when a single dashboard combines multiple assets.
Another sensitive moment comes during a major market change. A falling portfolio can make me want to edit values repeatedly or remove disappointing holdings from the overview. I would resist using the tracker to rewrite reality. If a value has changed, I would update it consistently; if my investment plan needs changing, I would make that decision outside the emotional rush of a single screen.
Sumio is also not a substitute for secure access to a financial institution. I would not use a tracking screen as proof that a transaction has settled, an account is protected, or a tax figure is final. For those questions, I would go to the original provider or appropriate professional source. The app’s role is organization and perspective, not official confirmation.
Who will get the most from it
I think Sumio fits people who have started accumulating money in several places and want one personal overview. It could be useful for an investor with stocks and funds, someone tracking savings alongside other assets, or a household that wants to review progress without opening multiple services. It may also suit a person who prefers deliberate manual review over a constantly changing feed.
It is especially appropriate for users willing to maintain their entries. A tracker becomes valuable when the information is reasonably current and categorized in a consistent way. If I update only once and never return, the dashboard may become an attractive but outdated snapshot.
The app may be less suitable for someone who wants automatic, real-time synchronization across every financial institution, detailed spending analytics, or professional portfolio management. I would also hesitate to recommend it as the only financial tool for a person who needs tax reporting, debt payoff planning, or a formal investment analysis platform. Those needs call for more specialized services.
Compared with a spreadsheet, Sumio should feel more purpose-built for net-worth and portfolio review, while a spreadsheet offers greater freedom to create formulas, notes, and custom reports. Compared with a banking app, Sumio has a broader personal-asset perspective, but a bank remains the authoritative place for account activity. Compared with a budgeting app, Sumio focuses more on accumulated wealth than on where every recent payment went. The better choice depends on the question I ask most often.
Platform details and everyday usability
Sumio is available as an Android app, and it supports devices running Android seven point zero or later. The current version is one point nine eighteen. Its content rating is Everyone, which makes it broadly approachable from an age-rating perspective, although the financial subject matter is naturally more relevant to people managing their own money.
The app has passed ten thousand installs and holds a three point eight average from seventy-eight ratings, alongside five written reviews. I read that as a modest public footprint rather than overwhelming evidence either way. The rating suggests that experiences are mixed enough for me to test the workflow personally instead of assuming it will suit every investor.
One detail I appreciate about a focused tracker is the possibility of reducing mental clutter. I do not need every financial task inside one application if a clear wealth snapshot is the main goal. But that benefit depends on the interface making updates easy enough to repeat. If recording a new value requires too many steps, I would eventually return to a spreadsheet or a simple note, even if the app looks more polished.
Three habits that make the app more dependable
First, I would create a baseline before making changes. Record the current picture, note the date, and then use later updates to compare against that starting point. This is more informative than judging the app by a single total because it shows whether the tracking process helps me notice trends.
Second, I would review categories for double counting. For example, if an investment account already includes a fund, I would not add the same fund again as a separate asset unless I am certain the entries represent different holdings. A consolidated tracker is only as accurate as its structure. Duplicate entries can make progress look better while quietly damaging the usefulness of every later comparison.
Third, I would keep estimated assets from dominating decisions. If I include a property or personal possession, I would update its value conservatively and avoid interpreting small changes as genuine financial progress. Liquid investments and cash deserve a different level of confidence from assets that are difficult to sell or price.
These habits are not flashy features, but they are where I see the real value of Sumio. The app can give me a convenient framework; disciplined input determines whether that framework tells the truth well enough to guide a decision.
My cautious verdict
After reviewing Sumio as a finance tool, I see a sensible use case: building a personal net-worth picture that includes investments, stocks, funds, and other assets. I like the idea of checking financial progress from one focused view rather than mentally combining figures from unrelated apps. The free starting point also makes it reasonable to test the experience before considering any optional purchase.
My reservations are equally practical. The app should not be treated as a live brokerage, a bank replacement, or a tax system. Its usefulness depends on accurate, timely entries, and the more sensitive the information I add, the more carefully I should review account controls, privacy choices, and what is actually necessary. I would also avoid paying until I know which paid functions solve a real problem in my routine.
For someone who wants a calm monthly overview of personal wealth, Sumio could be a good fit. For someone seeking automatic financial aggregation, detailed budgeting, or professional-grade analysis, another category of tool is likely better. My recommendation is to begin with a limited set of entries, establish a dated baseline, and judge the app by whether it helps me make clearer decisions without encouraging false precision.
In short, Sumio: Net Worth Tracker is most convincing when I use it as a personal checkpoint rather than an authority. It can organize the financial picture I choose to maintain, surface useful changes, and make scattered assets easier to consider together. The final responsibility remains mine: protect sensitive information, question uncertain valuations, and use the overview to support—not replace—sound financial judgment.
Frequently Asked Questions
What is Sumio: Net Worth Tracker used for?
Sumio: Net Worth Tracker is a personal finance app designed to help you monitor your overall financial position in one place. You can record assets such as bank accounts, investments, property, and digital currencies, then compare them with debts and other liabilities. The app focuses on net worth tracking and financial progress rather than replacing a full banking or budgeting service.
How does Sumio calculate my net worth?
The app calculates net worth by subtracting your total liabilities from your total assets. You can add accounts and values manually, organize them into categories, and update balances as they change. Depending on the version and available integrations, some information may be synchronized automatically, while other figures require manual updates. Reviewing entries regularly is important because the results are only as accurate as the data provided.
Can I use Sumio to track investments, debts, and multiple currencies?
Sumio is built to support a broad view of personal finances, so it can be useful for tracking investments, loans, credit card balances, property, savings, and other valuable possessions. Users with accounts in different currencies should check the current app settings and supported currency options before relying on automatic conversions. Investment values may also need verification, particularly when prices or exchange rates change frequently.
Is my financial information safe in Sumio?
Before adding sensitive financial details, review Sumio’s privacy policy, security information, and the permissions requested by the current app version. If the app offers account connections, confirm whether it uses a trusted secure connection and whether credentials are stored by Sumio or an external provider. For extra protection, use a strong device passcode, enable biometric access when available, and avoid entering unnecessary confidential information.
Is Sumio: Net Worth Tracker free to download and use?
Sumio may be available to download at no initial cost, but certain features can depend on a subscription, in-app purchase, or plan limitations. Premium options may include expanded account tracking, advanced charts, synchronization, customization, or additional financial tools. Pricing and included features can vary between Android and iOS and may change over time, so check the store listing and in-app purchase screen before subscribing.


